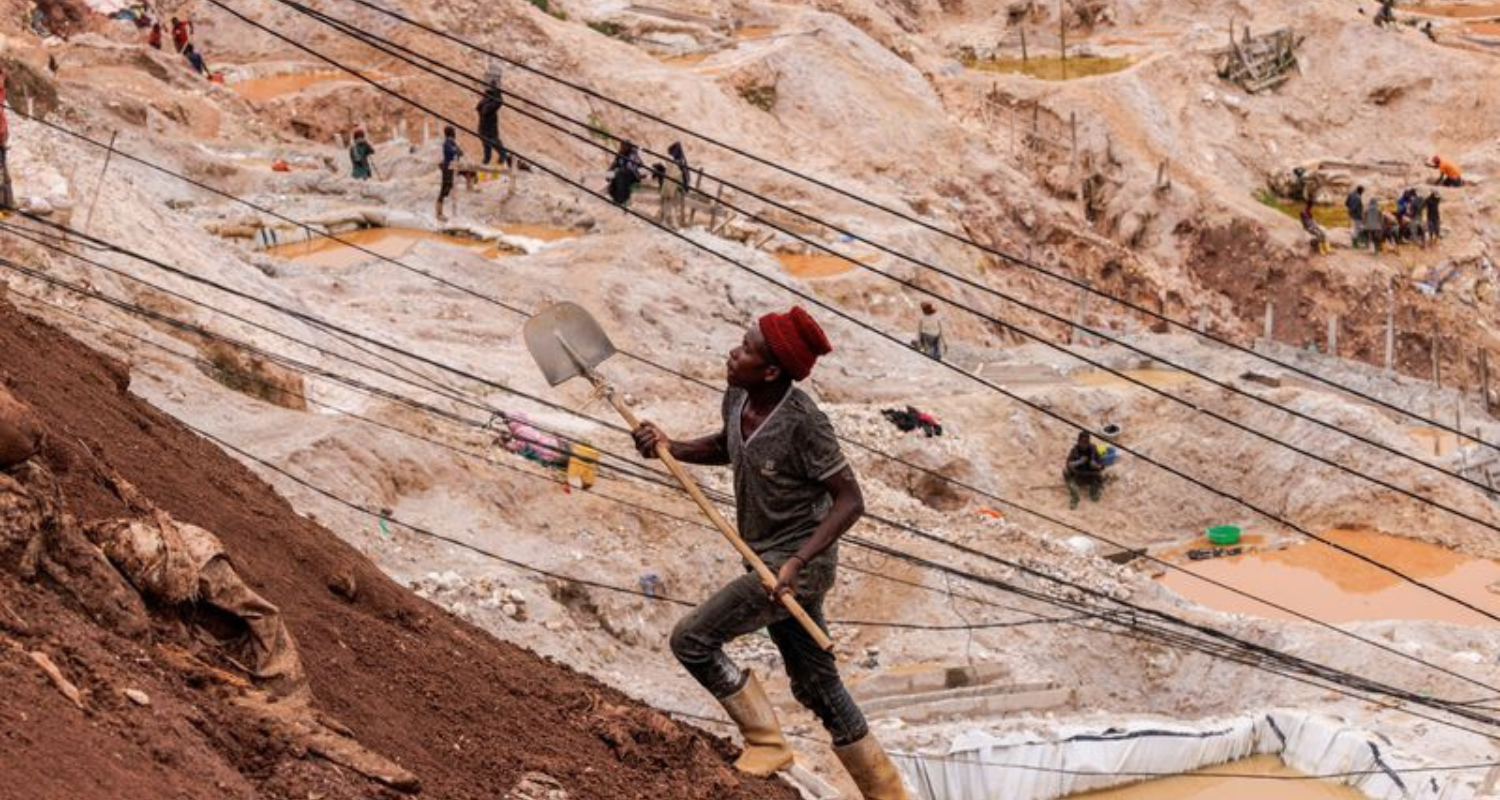
At Angola’s Atlantic port of Lobito, Washington’s ambitions take a tangible shape: railway tracks, mineral shipments and a route connecting Africa’s interior to global markets. The infrastructure is becoming a central piece of an American effort to diversify access to critical minerals and challenge China’s influence over the supply chains behind advanced industries.
The next phase could bring more than additional loans. The U.S. International Development Finance Corporation, or DFC, plans to expand direct equity investments, including in African critical mineral projects. That approach would give the agency ownership stakes in selected ventures, tying American capital more closely to their commercial fortunes.
For African governments and investors, the emerging question is not simply how much money Washington will commit. It is what that money will build, which risks it will absorb and whether mineral wealth can support economic activity beyond extraction.
A More Direct Stake in Africa’s Resources
The DFC’s investment ambitions came into sharper focus on October 9, when its Africa head, Vibhuti Jain, told Reuters that the agency intended to increase equity investing. Its commitments across Africa already exceed $14 billion, including more than $3 billion directed toward critical minerals and related investments. Those figures describe existing commitments, not a newly announced funding package.
The distinction matters. Washington is signaling a broader investment direction rather than unveiling a single pot of fresh money with a fixed allocation. Reuters reported that additional equity investments were in the pipeline, but officials did not identify which projects would receive them. The agency’s wider minerals pipeline includes rare earth developments and a graphite mine in Mozambique.
An equity stake changes the relationship between financier and project. Instead of relying solely on repayment, an investor participates in a venture’s gains and losses. For Washington, that creates a more direct commercial interest in the assets it supports. It also makes project selection consequential: strategic appeal must sit alongside a credible path to commercial success.
The Railway Behind the Strategy
The most visible expression of the American approach is the Lobito Corridor, which is intended to connect mineral-producing areas of the Democratic Republic of Congo and Zambia with Angola’s Atlantic coast. Its importance lies in the connection between resources and infrastructure. Access to deposits is only part of the challenge; moving their output reliably and competitively is another.
In December 2025, the DFC signed a $553 million loan agreement supporting the Lobito Atlantic Railway. The financing covers rehabilitation and operation of approximately 1,300 kilometers of railway in Angola, running between Lobito and Luau near the Congolese border, together with mineral-port infrastructure. The Development Bank of Southern Africa is providing an additional $200 million.
The DFC projects that the investment will increase transportation capacity tenfold to 4.6 million metric tons and reduce critical mineral transport costs by as much as 30 percent. These remain projected benefits, not completed results. Nevertheless, they explain why a railway occupies such a prominent place in a strategy often described primarily in terms of mines. Infrastructure can determine whether mineral deposits become dependable commercial supply.
Competition Extends Beyond the Mine
Washington’s push is part of a wider effort to counter China’s dominance of key supply chains. The DFC’s planned expansion links development finance with an increasingly explicit strategic objective: building alternatives in sectors where concentrated supply creates economic vulnerability. Africa’s mineral projects offer potential entry points, although financing them does not automatically deliver operating mines or finished materials.
Rare earth projects illustrate the gap between commitment and production. Reuters reported in August that the DFC had committed $62.8 million to projects in Malawi, Angola, Madagascar and South Africa, with none yet producing. Approximately $50 million of that total supported South Africa’s Phalaborwa project. Public backing was helping advance developments that private investors had been reluctant to finance.
The lesson is less dramatic than the language of a mineral race suggests. Capital can help projects move forward, but announced investment is not the same as new supply. Washington’s approach will ultimately be judged by what reaches production and whether those operations can become commercially sustainable, rather than by the size of commitments alone.
Africa’s Opportunity Is Bigger Than Extraction
The financing landscape is also widening beyond American bilateral investment. Zambia, Egypt, Malawi and Mauritania are among the first countries selected for a World Bank Group initiative targeting $19 billion in minerals financing and private capital mobilization through 2030. That target combines institutional support and mobilized investment; it is not $19 billion in new lending earmarked for Africa.
The initiative encompasses mining, processing and supporting infrastructure, placing the discussion beyond the mine gate. For participating African countries, those categories provide a useful framework for assessing prospective deals: whether investment supports only the movement of raw materials or also strengthens the systems and businesses around them.
America’s expanding interest therefore creates an opening, not a guaranteed transformation. Its value will depend on execution: projects reaching operation, infrastructure delivering its promised efficiencies and investment terms aligning commercial returns with host-country priorities. Along the railway to Lobito, the larger contest is becoming concrete. The test is whether strategic attention can become productive assets, rather than another cycle of ambitious announcements.